 hseipaa.kz




Filing tax reporting
We prepare and check tax reporting, monitor deadlines and compliance with requirements. We help reduce the risk of errors, notices and additional assessments, providing clear support at every stage.
 Monthly, quarterly, semi-annual and annual reporting
 Remotely via digital signature or in person
 We will set up the issuing of electronic invoices (ESF)

0
Why this is convenient
We will prepare and file all tax and statistical reporting: remotely via the internet using your electronic digital signature keys, or in person if you are in Almaty, Astana, Taraz, Atyrau or Aktau.

We work remotely across Kazakhstan

We prepare tax and statistical forms

We will set up the issuing of electronic invoices
What we take on
 Preparation of tax reporting
Filing of monthly, quarterly, half-yearly and annual reports
Statistical reporting forms
Issuing electronic invoices (ESF)
Electronic submission of reports
Presence at the tax authority by arrangement
Consultations on tax forms
Advantages of working with us
Your tax reporting will be handled by specialists with many years of practice.

Meeting deadlines
We monitor the calendar and file tax returns on time.

Data verification
We reconcile accounting indicators before preparing returns and calculations.

Risk reduction
We help you avoid errors, notices and additional charges.

Current requirements
We take into account current reporting forms and changes in legislation.

Confidentiality
We protect the client's financial and tax information.

Feedback
We explain reporting indicators and report on the actions taken.
What we need from you
To file your reports on time, minimal action is required on your part.

Digital signature keys
For submitting reports via the internet

Primary documents
Data for the reporting period

Dates
Timely transfer of information

Confirmation
Approval of the prepared reports
Which companies we take on for service
LLP
Sole proprietors
JSC
Joint companies
Natural monopolies
Associations
Public associations
Tax and statistical reporting
We file tax forms 200.00, 700.00, 910.00, 240.00 and others, as well as statistical reports for sole proprietors, LLPs, JSCs, joint ventures, associations and public associations.

from 1 000 ₸
Zero tax reporting in electronic form.

from 500 ₸
Submission of nil statistical reports in electronic form.

All of Kazakhstan
We work remotely and in person in the country's major cities.
- preparation of returns and electronic submission of reports
- individual income tax and social tax return
- declaration on vehicle tax, land tax and property tax
- a simplified return for small business entities
- preparation and submission of statistical reporting forms
- setting up and issuing electronic invoices
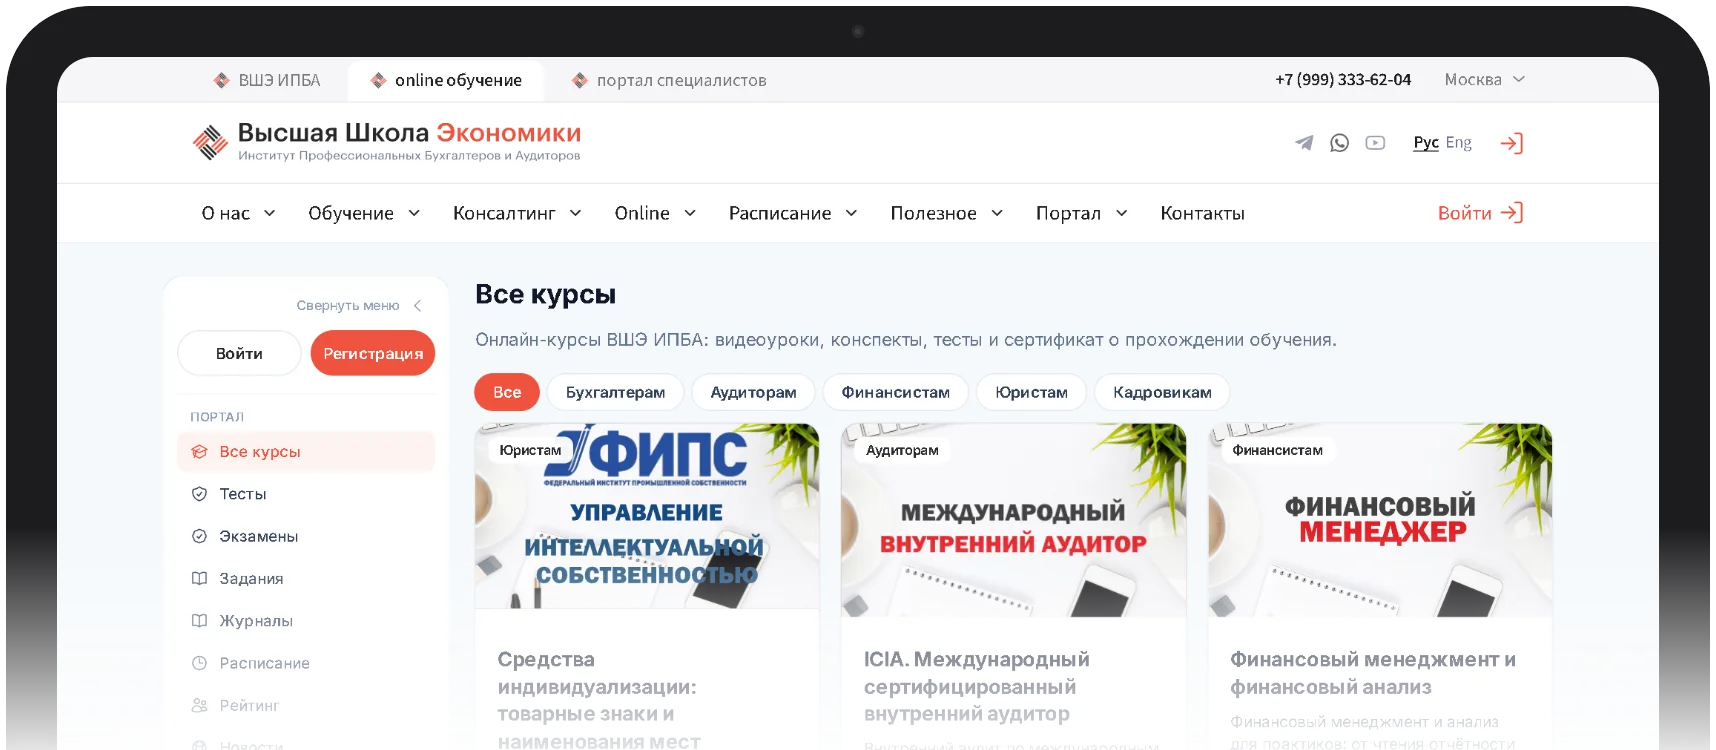
A convenient learning platform
A personal account with a clear interface: manage your training, track your progress and communicate with instructors in one place.
Training materials
All lectures, presentations and assignments in one place
Class schedule
A calendar with reminders of upcoming classes
Progress
Progress and completed assignments
Video lectures
Watch lectures at a convenient time
FAQ
Frequently asked questions about the "Tax Reporting Submission" service
Didn't find an answer? Ask a question — a manager will reply and help you choose a program.
Ask a question01 What does the «Tax Reporting Submission» service include?
The scope of work is determined after analysing the client's task. We agree on the stages, expected result, timing and list of required documents, and then record them in the proposal.
02 Who is this service suitable for?
The service is suitable for companies and entrepreneurs who need professional support in the area of “Tax Reporting Filing” without expanding their own team.
03 How is the project work organised?
Work begins with a consultation and diagnostics. We then draw up a plan, assign responsible specialists, carry out the agreed stages and deliver the results to the client.
04 What do timelines and cost depend on?
Timing and cost depend on the scope of work, the condition of the source data, the complexity of the task and the required depth of support. Exact terms are determined after an initial assessment.
05 How is confidentiality ensured?
The client's information and documents are used only to carry out the agreed work. Access to them is granted to the specialists directly involved in the project.
About the “Filing tax reporting” service
Filing of tax reporting throughout Kazakhstan. Preparation of tax reporting. Your tax reporting will be handled by the best specialists in their field.
We will prepare and file all tax reporting throughout Kazakhstan
- remotely via the internet - you will need to provide your EDS (electronic digital signature) keys
- in person, if you are in Almaty, Astana, Taraz, Atyrau or Aktau
Filing of monthly, quarterly, half-yearly and annual tax and statistical reporting
Which companies we can take on for servicing
- LLP
- IE (individual entrepreneurs)
- JSC
- Joint companies
- Natural monopolies
- Associations
- Public associations
We file the following tax forms:
- 200.00 - declaration on individual income tax and social tax for citizens of Kazakhstan
- 700.00 - declaration on vehicle tax, land tax and property tax
- 910.00 - simplified declaration for small business entities
- 240.00 - declaration on individual income tax
The other reporting forms are given below
We file all statistical forms
Filing statistical forms is also an important part of keeping business records. Statistical reporting forms are filed by individual entrepreneurs as well as by LLPs, JSCs, joint ventures, associations, public associations, etc.
Issuing electronic invoices (ESF)
We will prepare and set up the issuing of electronic invoices.
How tax and statistical reports are filed
In most cases all tax reporting is filed electronically, but if you need our presence at the tax authority and/or the statistics office, this is discussed separately
Cost of filing tax and statistical reporting
Nil tax reporting (electronic) - from 1 000 tenge
Nil statistical reporting (electronic) - from 500 tenge
The remaining cost is discussed separately, but do not worry: the prices will pleasantly surprise you. for all questions, call - 8 707 553 33 83
Which tax reports we file
|
Corporate income tax
|
|
|
Form 032.00 |
Procedure for submitting tax reporting (declaration) of the office of the commissioner of the section «Nur-Sultan (Astana) EXPO-2024» (form 032.00) |
|
Form 100.00 |
Rules for preparing tax reporting (declaration) on corporate income tax (form 100.00) Requirements for format and logic control when preparing tax reporting (declaration) on corporate income tax (form 100.00) Regulatory framework for completing the form Other explanatory materials on completing the form See also: Line-by-line completion of the CIT declaration in form 100.00 for 2024; Template for completing the CIT declaration in form 100.00 for 2024 in the format Excel |
|
Form 101.01 |
Rules for preparing tax reporting (calculation) of the amount of advance payments of corporate income tax payable for the period before filing the declaration, and tax reporting (calculation) of the amount of advance payments of corporate income tax payable for the period after filing the declaration (forms 101.01 - 101.02) Requirements for format and logic control when preparing tax reporting (calculation) of the amount of advance payments of corporate income tax payable for the period before filing the declaration (form 101.01) Requirements for format and logic control when preparing tax reporting (calculation) of the amount of advance payments of corporate income tax payable for the period after filing the declaration (form 101.02) See also: Line-by-line completion of the calculation of the amount of advance payments of CIT payable for the period before filing the declaration in form 101.01 and of the calculation of the amount of advance payments of CIT payable for the period after filing the declaration in form 101.02 for 2024 |
|
Form 101.02 |
|
|
Form 101.03 |
Rules for preparing tax reporting (calculation) on corporate income tax withheld at the source of payment from the income of a resident (form 101.03) Requirements for format and logic control when preparing tax reporting (calculation) on corporate income tax withheld at the source of payment from the income of a resident (form 101.03) See also: Line-by-line completion of the calculation of CIT withheld at the source of payment from the income of a resident, in form 101.03 for Q4 2024 |
|
Form 101.04 |
Rules for preparing tax reporting (calculation) on corporate income tax withheld at the source of payment from the income of a non-resident (form 101.04) Requirements for format and logic control when preparing tax reporting (calculation) on corporate income tax withheld at the source of payment from the income of a non-resident (form 101.04)
See also: Line-by-line completion of the calculation of CIT withheld at the source of payment from the income of a non-resident, in form 101.04 for Q1 2024 |
|
Form 110.00 |
Rules for preparing tax reporting (declaration) on corporate income tax (form 110.00) Requirements for format and logic control when preparing tax reporting (declaration) on corporate income tax (form 110.00) See also: Line-by-line completion of the corporate income tax declaration in form 110.00 for 2024 |
|
Form 130.00 |
Rules for preparing tax reporting (declaration) on corporate income tax (form 130.00) Requirements for format and logic control when preparing tax reporting (declaration) on corporate income tax (form 130.00) See also: Line-by-line completion of the CIT declaration for non-profit organisations in form 130.00 for 2024; Template for completing the CIT declaration for non-profit organisations in form 130.00 for 2024 in the format Excel |
|
Form 150.00 |
Rules for preparing tax reporting (declaration) on corporate income tax (form 150.00) Requirements for format and logic control when preparing tax reporting (declaration) on corporate income tax (form 150.00) See also: Line-by-line completion of the CIT declaration in form 150.00 for 2024; Template for completing the CIT declaration in form 150.00 for 2024 in the format Excel |
|
Individual income tax and social tax
|
|
|
Form 200.00 Applies to obligations to submit tax reporting forms (FNO) until 9 June 2024 |
Rules for preparing tax reporting (declaration) on individual income tax and social tax for citizens of Kazakhstan (form 200.00) The Rules apply to obligations to submit tax reporting forms (FNO) until 9 June 2024 Requirements for format and logic control when preparing tax reporting (declaration) on individual income tax and social tax for citizens of Kazakhstan (form 200.00) See also: Line-by-line completion by individual entrepreneurs of the PIT and social tax declaration for citizens of Kazakhstan in form 200.00 for Q1 2024; Template for completing the declaration in form 200.00 for Q1 2024 in the format Excel Line-by-line completion by legal entities of the PIT and social tax declaration for citizens of Kazakhstan in form 200.00 for Q1 2024 |
|
Form 200.00 Applies to obligations to submit tax reporting forms (FNO) from 9 June 2024 |
Rules for preparing tax reporting (declaration) on individual income tax and social tax (form 200.00) The Rules apply to obligations to submit tax reporting forms (FNO) from 9 June 2024
Requirements for format and logic control when preparing tax reporting (declaration) on individual income tax and social tax for citizens of Kazakhstan (form 200.00)
See also: Line-by-line completion of the PIT and social tax declaration in form 200.00 for Q2 2024 by individual entrepreneurs applying the general taxation regime Line-by-line completion of the PIT and social tax declaration in form 200.00 for Q2 2024 by a legal entity Line-by-line completion of Appendix 200.03 Line-by-line completion of the declaration in form 200.00 by a legal entity for the 3rd and 4th quarters of 2024 Template for completing the declaration in form 200.00 by a legal entity for the 3rd and 4th quarters of 2024 in the format Excel Line-by-line completion of the declaration in form 200.00 for the 3rd and 4th quarters of 2024 by IEs applying the general taxation regime Template for completing the declaration in form 200.00 by IEs applying the general taxation regime for the 3rd and 4th quarters of 2024 in the format Excel |
|
Form 210.00 and the Rules for its preparation were in effect from 1 January 2024 to 31 December 2024. Forms 200.00 and 210.00 have been merged into a single form of declaration on PIT and social tax (FNO 200.00), which comes into effect on 9 June 2024. See also: On the submission of declarations on PIT and social tax in forms 200.00 and 210.00 in 2024 Line-by-line completion of the PIT and social tax declaration for foreigners and stateless persons in form 210.00 for Q1 2024 |
|
|
Form 220.00 |
Rules for preparing tax reporting (declaration) on individual income tax (form 220.00) Requirements for format and logic control when preparing tax reporting (declaration) on individual income tax (form 220.00) See also: Line-by-line completion of the PIT declaration (form 220.00) for 2024 and an example of completion in the format Excel Template for completing the PIT declaration in form 220.00 for 2024 in the format Excel |
|
Form 230.00
|
Rules for preparing tax reporting (declaration) on individual income tax and property (form 230.00) Requirements for format and logic control when preparing tax reporting (declaration) on individual income tax and property (form 230.00) |
|
Form 240.00
|
Rules for preparing tax reporting (declaration) on individual income tax (form 240.00) Requirements for format and logic control when preparing tax reporting (declaration) on individual income tax (form 240.00) |
|
Value added tax, indirect taxes
|
|
|
Form 300.00 |
Rules for preparing tax reporting (declaration) on value added tax (form 300.00) Requirements for format and logic control when preparing tax reporting (declaration) on value added tax (form 300.00) See also: Line-by-line completion of the VAT declaration in form 300.00 for Q1-Q4 2024 Template for completing the VAT declaration in form 300.00 for Q1-Q4 2024 in the format Excel |
|
Form 320.00 |
Rules for preparing tax reporting (declaration) on indirect taxes on imported goods (form 320.00) Requirements for format and logic control when preparing tax reporting (declaration) on indirect taxes on imported goods (form 320.00) See also: Line-by-line completion of the declaration on indirect taxes on imported goods (form 320.00) in 2024 Template for completing the declaration on indirect taxes on imported goods (form 320.00) in 2024 in the format Excel |
|
Form 328.00 |
Rules for completing and submitting the application on the import of goods and payment of indirect taxes (form 328.00) See also: Line-by-line completion of the application on the import of goods and payment of indirect taxes (form 328.00) in 2024 |
|
Excise duties
|
|
|
Form 400.00 |
Rules for preparing tax reporting (declaration) on excise duty (form 400.00) Requirements for format and logic control when preparing tax reporting (declaration) on excise duty (form 400.00) See also Line-by-line completion of the excise duty declaration (form 400.00) in 2024 |
|
Form 421.00 |
Rules for preparing tax reporting (calculation) of excise duty for a structural unit or objects related to taxation (form 421.00) Requirements for format and logic control when preparing tax reporting (declaration) of excise duty for a structural unit or objects related to taxation (form 421.00) See also Line-by-line completion of the calculation of excise duty for a structural unit or objects related to taxation (form 421.00) for 2024 |
|
Subsoil users
|
|
|
Form 500.00 |
Rules for preparing tax reporting (declaration) on royalty, production bonus, the share of Kazakhstan under production sharing, and the additional payment of a subsoil user operating under a production sharing contract (form 500.00) Requirements for format and logic control when preparing tax reporting (declaration) on royalty, production bonus, the share of Kazakhstan under production sharing, and the additional payment of a subsoil user operating under a production sharing contract (form 500.00) See also: Recommendations on completing the declaration on royalty, production bonus, the share of Kazakhstan under production sharing, and the additional payment of a subsoil user operating under a production sharing contract (form 500.00) |
|
Form 510.00 |
Rules for preparing tax reporting (declaration) on the signature bonus and commercial discovery bonus (form 510.00) Requirements for format and logic control when preparing tax reporting (declaration) on the signature bonus and commercial discovery bonus (form 510.00) See also: Line-by-line completion of the declaration on the signature bonus and commercial discovery bonus (form 510.00) for 2024 |
|
Form 531.00 |
Rules for preparing tax reporting on the calculation of the amounts and deadlines for payment (transfer) of the share of Kazakhstan under production sharing, established by the subsoil use contract, in kind (form 531.00) |
|
Form 540.00 |
Rules for preparing tax reporting (declaration) on windfall profit tax (form 540.00) Requirements for format and logic control when preparing tax reporting (declaration) on windfall profit tax (form 540.00) See also Line-by-line completion of the windfall profit tax declaration (form 540.00) for 2024 |
|
Form 560.00 |
Rules for preparing tax reporting (declaration) on the payment for reimbursement of historical costs (form 560.00) Requirements for format and logic control when preparing tax reporting (declaration) on the payment for reimbursement of historical costs (form 560.00) See also Line-by-line completion of the declaration on the payment for reimbursement of historical costs in form 560.00 for 2024, 2024 |
|
Form 570.00 |
Rules for preparing tax reporting (declaration) on export rent tax (form 570.00) Requirements for format and logic control when preparing tax reporting (declaration) on export rent tax (form 570.00) See also Line-by-line completion of tax reporting (declaration) on export rent tax (form 570.00) for 2024 |
|
Form 590.00 |
Rules for preparing tax reporting (declaration) on mineral extraction tax (form 590.00) Requirements for format and logic control when preparing tax reporting (declaration) on mineral extraction tax (form 590.00) See also Line-by-line completion of tax reporting (declaration) on mineral extraction tax (form 590.00) for 2024 |
|
Form 641.00 |
Rules for preparing tax reporting (calculation) of contributions to the employment promotion, compulsory medical insurance and state social insurance funds, the state pension payment centre and contributions of road users (form 641.00) Requirements for format and logic control when preparing tax reporting (calculation) of contributions to the employment promotion, compulsory medical insurance and state social insurance funds, the state pension payment centre and contributions of road users (form 641.00) |
|
Local taxes
|
|
|
Form 700.00 |
Rules for preparing tax reporting (declaration) on vehicle tax, land tax and property tax (form 700.00) Requirements for format and logic control when preparing tax reporting (declaration) on vehicle tax, land tax and property tax (form 700.00) See also: Line-by-line completion of the declaration on vehicle tax, land tax and property tax in form 700.00 for 2024; Tax registers for property tax for 2024 in the format Excel; Tax registers for vehicle tax for 2024 in the format Excel |
|
Form 701.00 |
Rules for preparing tax reporting (calculation) of current payments of vehicle tax (form 701.00) Requirements for format and logic control when preparing tax reporting (calculation) of current payments of vehicle tax (form 701.00) See also: Tax registers for vehicle tax for 2024 in the format Excel Line-by-line completion of tax reporting (calculation) of current payments of vehicle tax (form 701.00) for 2024 |
|
Form 701.01 |
Rules for preparing tax reporting (calculation) of current payments of land tax and property tax (form 701.01) Requirements for format and logic control when preparing tax reporting (calculation) of current payments of land tax and property tax (form 701.01) See also: Line-by-line completion of the calculation of current payments of property tax and land tax in form 701.01 in 2024; Calculation of tax on property and land for IEs for 2024; On the submission of the calculation of current payments of land tax and property tax in form 701.01 in 2024; Tax registers for property tax for 2024 in the format Excel |
|
Gambling business tax
|
|
|
Form 710.00 |
Rules for preparing tax reporting (declaration) on gambling business tax and fixed tax (form 710.00) Requirements for format and logic control when preparing tax reporting (declaration) on gambling business tax and fixed tax (form 710.00) Line-by-line completion of the declaration on gambling business tax and fixed tax in form 710.00 for Q1-Q4 2024 |
|
Other mandatory payments
|
|
|
Form 810.00 |
Rules for preparing tax reporting (declaration) on the auction fee and payment for the use of navigable waterways (form 810.00) Requirements for format and logic control when preparing tax reporting (declaration) on the auction fee and payment for the use of navigable waterways (form 810.00) |
|
Form 851.00 |
Rules for preparing tax reporting (calculation) of the amounts of current payments for the use of land plots (form 851.00) Requirements for format and logic control when preparing tax reporting (calculation of the amounts of current payments) on payment for the use of land plots (form 851.00) See also: Line-by-line completion of the declaration on payment for the use of land plots (form 851.00) for 2024; On the submission of the calculation of the amounts of current payments for the use of land plots in form 851.00 in 2024 |
|
Form 860.00 |
Rules for preparing tax reporting (declaration) on payment for the use of water resources of surface sources (form 860.00) Requirements for format and logic control when preparing tax reporting (declaration) on payment for the use of water resources of surface sources (form 860.00) |
|
Form 870.00 |
Rules for preparing tax reporting (declaration) on payment for emissions into the environment (form 870.00) Requirements for format and logic control when preparing tax reporting (declaration) on payment for emissions into the environment (form 870.00) Line-by-line completion of the declaration on payment for emissions into the environment in form 870.00 in 2024 |
|
Form 871.00 New form from 2024 |
Rules for preparing the register of lease (use) agreements (form 871.00) See also: Preparation of the register of lease (use) agreements in form 871.00 from 2024 |
|
Special tax regimes |
|
|
Form 910.00 Applies to obligations to submit tax reporting forms (FNO) until 1 July 2024 |
Rules for preparing tax reporting (simplified declaration) for small business entities (form 910.00) The Rules apply to obligations to submit tax reporting forms (FNO) until 1 July 2024 Requirements for format and logic control when preparing tax reporting (simplified declaration) for small business entities (form 910.00) See also: Preparation of tax reporting in form 910.00 by IEs applying the special tax regime (STR) on the basis of a simplified declaration (without employees), for H1 2024; Preparation of tax reporting in form 910.00 by IEs applying the special tax regime (STR) on the basis of a simplified declaration (with employees), for H1 2024; Template for completing the declaration in form 910.00 for H1 2024 in the format Excel |
|
Form 910.00 Applies to obligations to submit tax reporting forms (FNO) from 1 July 2024 |
Rules for preparing tax reporting (simplified declaration) for small business entities (form 910.00) The Rules apply to obligations to submit tax reporting forms (FNO) from 1 July 2024
See also: Line-by-line completion of the declaration in form 910.00 by IEs applying the STR on the basis of a simplified declaration, for H2 2024 Template for completing the declaration in form 910.00 by IEs applying the STR on the basis of a simplified declaration for H2 2024 in the format Excel Line-by-line completion of the declaration in form 910.00 by LLPs applying the STR on the basis of a simplified declaration, for H2 2024 Template for completing the declaration in form 910.00 by LLPs applying the STR on the basis of a simplified declaration for H2 2024 in the format Excel |
|
Form 911.00 Applies to obligations to submit tax reporting forms (FNO) until 1 July 2024 |
Rules for preparing tax reporting (calculation) of the patent cost (form 911.00) The Rules apply to obligations to submit tax reporting forms (FNO) until 1 July 2024 Requirements for format and logic control when preparing tax reporting (calculation) of the patent cost (form 911.00) See also: Line-by-line completion of the calculation for obtaining a patent (form 911.00) for 2024 (until 1 July) |
|
Form 911.00 Applies to obligations to submit tax reporting forms (FNO) from 1 July 2024 |
Rules for preparing tax reporting (calculation) of the patent cost (form 911.00) The Rules apply to obligations to submit tax reporting forms (FNO) from 1 July 2024
See also: Line-by-line completion of the calculation for obtaining a patent (form 911.00) for 2024 (from 1 July) Line-by-line completion of the additional calculation for obtaining a patent (form 911.00) for 2024 on contributions to compulsory social medical insurance (CSMI) |
|
Form 920.00 Applies to obligations to submit tax reporting forms (FNO) until 1 July 2024 |
Rules for preparing tax reporting (declaration) for single land tax payers (form 920.00) The Rules apply to obligations to submit tax reporting forms (FNO) until 1 July 2024 Requirements for format and logic control when preparing tax reporting (declaration) for single land tax payers (form 920.00) |
|
Form 920.00 Applies to obligations to submit tax reporting forms (FNO) from 1 July 2024 |
Rules for preparing tax reporting (declaration) for single land tax payers (form 920.00) The Rules apply to obligations to submit tax reporting forms (FNO) from 1 July 2024
See also: Line-by-line completion of the declaration for single land tax payers in form 920.00 for 2024 |
Not sure which program to choose?
Our specialists will help you choose a program for your goals and answer all your questions. The consultation is free!
Reach us in one click: call us.
+7 (727) 224-21-21
contact us via messengers


